
Construction is one of the world's largest consumers of raw materials. Almost 50 per cent of global material extraction is attributable to the buildings and construction sector, according to the Global Status Report for Buildings and Construction 2025-2026 by UNEP and GlobalABC. Switzerland's material stock illustrates the enormous quantities held in buildings and infrastructure over decades: in 2015, its structures contained around 3.17 billion tonnes of material. Gravel and sand, asphalt, concrete and masonry accounted for 93 per cent. Concrete alone represented 42 per cent, at around 1.32 billion tonnes. Michael Scharpf roughly extrapolates this scale to Germany using a factor of nine. This would mean that several tens of billions of tonnes of material have accumulated in Germany's buildings and infrastructure over the years. As Head of Sustainable Construction at Holcim Germany, he explores how at least part of this vast raw-material stock can return to the material cycle after its use ends.
208 million tonnes of waste, yet too little recycled material
Germany's mineral construction waste gives an indication of the quantities released from this stock each year. In 2022, around 208 million tonnes were generated, according to the mineral raw materials association. Soil and stones make up the largest share, followed by construction rubble and road demolition waste. Yet these waste streams produce only around 75 million tonnes of recycled construction materials. This meets just 13 to 14 per cent of Germany's total demand for mineral construction materials.
For Michael Scharpf, a different approach is therefore essential. Buildings and infrastructure must increasingly be understood as temporary material stores. After use, construction materials should not automatically become waste, but should wherever possible serve as raw materials for new products. Recycling rates in some segments are already high. Holcim cites around 80 per cent for construction rubble and around 90 per cent for road demolition waste. The problem is therefore not solely whether materials are recovered, but what they are subsequently used for. Much of the recycled material goes into road and railway construction or other lower-value applications. Of the approximately 75 million tonnes of recycled construction materials, only around 14.5 million tonnes are available for concrete production.
Recycled concrete does not need to be invented
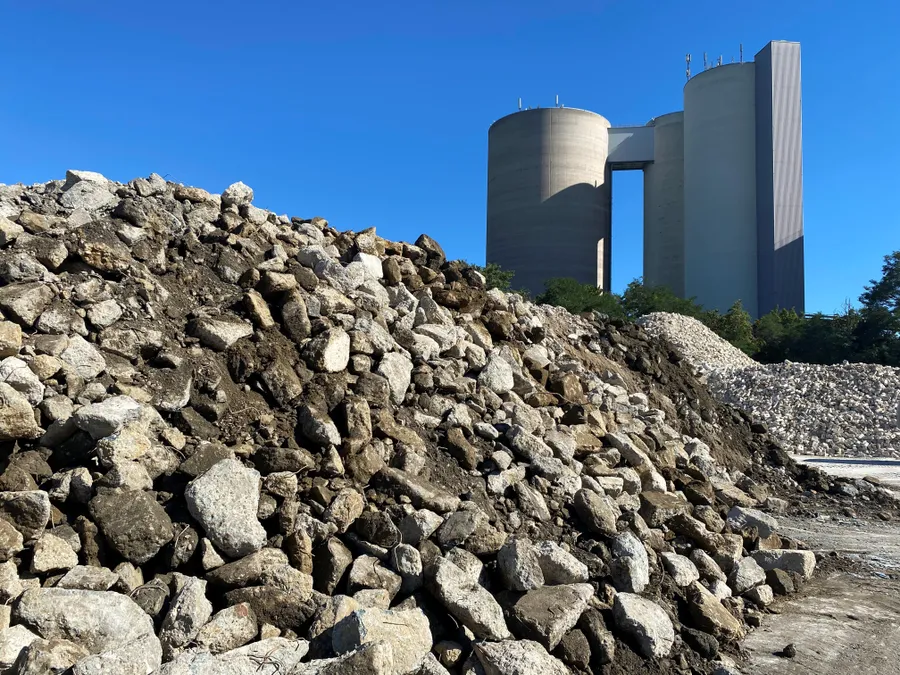
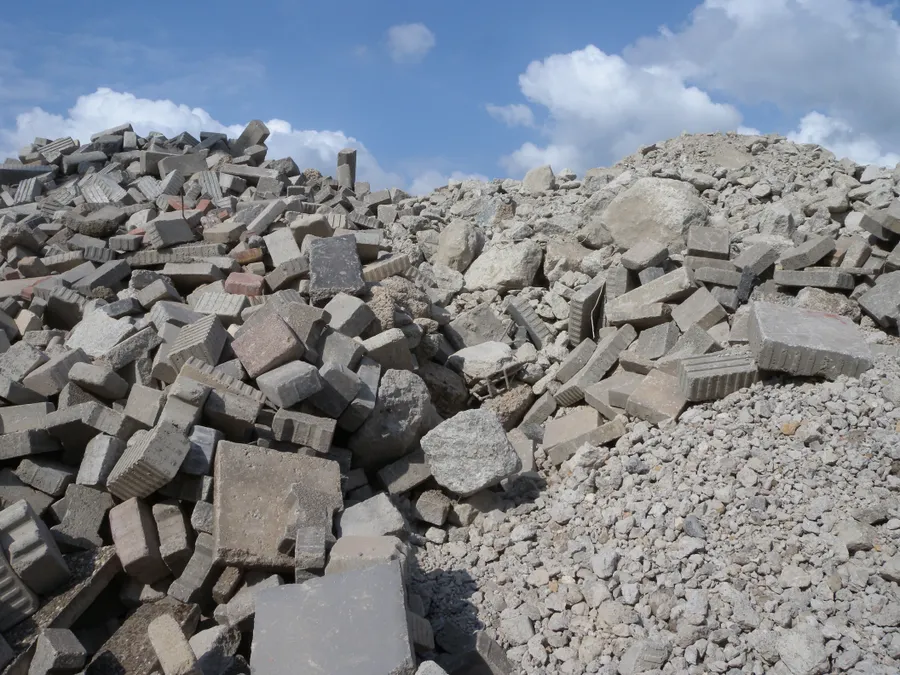
This has long been technically possible. Concrete can be recovered through selective demolition, then crushed, screened and separated into different fractions. Regulations define which recycled materials may be used in new concrete and in what quantities. A distinction is made, for example, between pure demolition concrete and mixed demolition material, which may also contain bricks, sand-lime bricks or other mineral constituents.
Recycled concrete is already used in various applications, including exposed concrete and watertight components. The technologies and standards therefore exist. Suitable source materials are also available in sufficient quantities and reliably return to production. Fractions that cannot be fully used as secondary aggregates in conventional concrete recycling are now also attracting interest. Holcim, for example, uses processed and finely ground demolition concrete as a cement constituent. According to Holcim, this recycled material can account for around 20 per cent of the weight of such cement. Holcim was the first company in Germany to receive general building authority approval for this, while a comparable recycled cement has been used in Switzerland for several years.
This can also improve the carbon footprint. Cement clinker is cement's particularly carbon-intensive main constituent, produced by firing mineral raw materials at very high temperatures. Reducing its proportion by using other suitable constituents also reduces the associated emissions. Resource conservation and climate protection can therefore complement one another. But they are not the same thing.
 Holcim
1 / 3
 Holcim
2 / 3
 Holcim
3 / 3
Reducing carbon emissions and conserving resources are different tasks
A life-cycle assessment addresses, among other things, the environmental impacts and carbon emissions caused by a construction material. It does not automatically show how effectively that material is kept in use. A recycled product can replace primary raw materials and prevent waste without necessarily achieving the greatest advantage in every carbon assessment.
Scharpf therefore speaks of two 'currencies'. One is the now established life-cycle assessment, with indicators such as carbon emissions. The other concerns resource consumption, waste prevention and circularity. He considers construction and real estate relatively advanced in life-cycle assessment, but far less consistent in material accounting.
This could play a greater role in selecting construction materials in future. Alongside price, technical performance and carbon footprint, more attention would be paid to how much primary material a product requires, which secondary raw materials it contains and what can happen to it after its first use. A construction material would not be considered sustainable solely because it achieves a low carbon figure.
Why the return journey is harder than delivery to site
There is a very practical reason why existing materials do not automatically return to production. New construction materials have established supply chains, usually drawing on a small number of raw-material sources. The return journey is much more fragmented. Demolition material must be collected, sorted, transported, accepted, checked and processed. At the same time, manufacturers need sufficiently large, continuously available quantities to supply recycled products reliably.
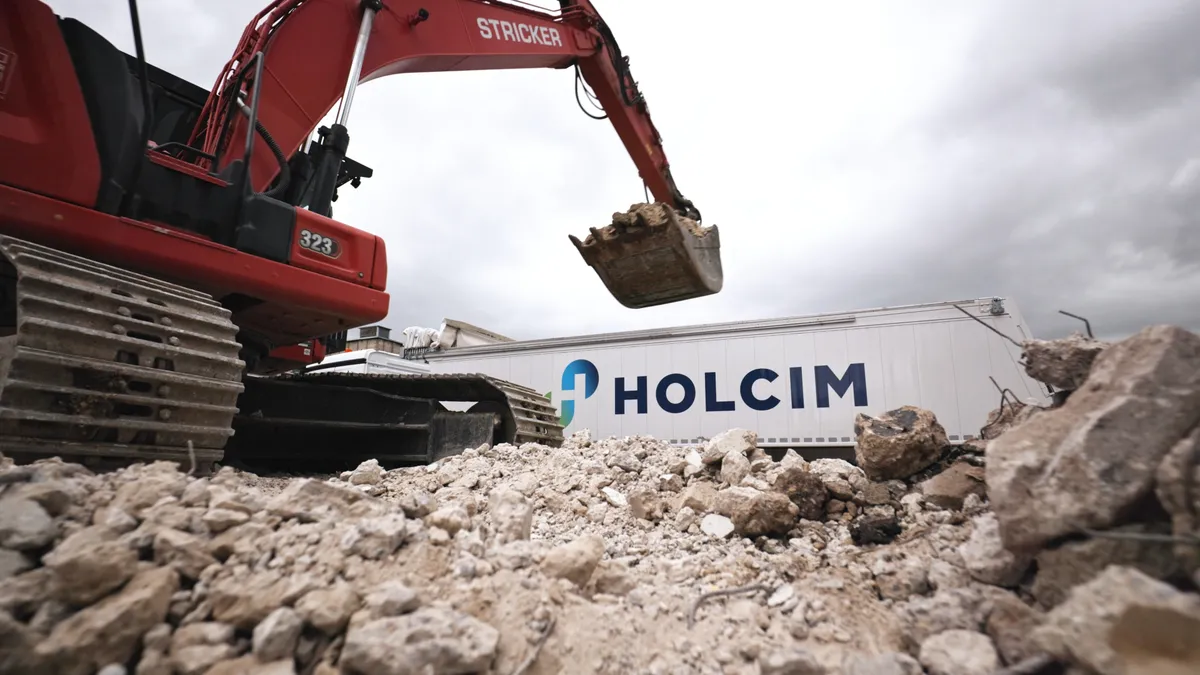
Holcim is developing recycling hubs for this purpose. These accept mineral demolition material and process it to a high standard. Such structures are intended to help organise reverse logistics. There is another important factor: recycled material is subject to stricter monitoring than primary material from a known deposit. Its composition depends on which structures are currently being dismantled. Manufacturers must therefore closely inspect incoming material streams and process them for the intended application.
Reusing entire components is even more demanding. It is not enough to know that a component could, in principle, be used again. The time and location of removal, its condition and properties, and a potential new buyer must also be known. The circular economy thus becomes a logistical task requiring supply and demand to coincide in time and place.
Without data, a building remains an unknown raw-material store
This is where digital information comes in. If a building is to serve as a material store in future, its constituents must remain identifiable and describable. Which materials were installed? In what quantities? What properties do they have? Can they be reused or recycled? And when are they expected to become available again?
Various approaches to assessment and documentation now exist. These include the Urban Mining Index (UMI), the Madaster Circularity Indicator, the DGNB Building Resource Passport and the Circular Transition Indicator of the World Business Council for Sustainable Development. The European Digital Product Passport will also make additional product information digitally available in future.
However, this also increases the number of datasets and assessment systems. One open question is which information is actually needed for decisions. Manufacturers, designers, operators and demolition companies have different requirements. Material flows themselves must also become digitally visible. A reusable component is of little use if nobody knows it will become available, or if supply and demand do not coincide in time or location.
Viewing a building as a raw-material store therefore sounds simple at first. In practice, that store needs a digital inventory. Only then can urban mining be organised on a larger scale.
Standards must also keep pace with the circular economy
Not every obstacle can be removed through technology and data. Some are embedded in regulations. Many standards and approval processes were developed for a construction industry in which new products are manufactured, tested and then installed. Reuse raises different questions.
Many applications of recycled concrete are now clearly regulated. Newer solutions, such as using recycled material in cement, required additional approvals. Entire components can be even more challenging. A product may have met every requirement when first installed. Decades later, different rules may apply, for example for fire protection. If the component is to be reused, its suitability under current conditions must be demonstrated.
Demountable structures and good material documentation therefore provide important foundations, but are not sufficient. A functioning circular economy also needs design processes, quality management and rules that enable used products to be employed again with legal certainty.
What is a construction material still worth after 30 years?
Alongside technology, data and standards comes an economic question: what value does a construction material have once installed? Conventional property valuation does not yet treat a building's material value as a separate component. In the worst case, materials are considered only in terms of demolition costs at the end of the use phase.
This logic is problematic for a circular economy. As raw materials become scarcer, the materials held in buildings may become more important. A concrete component, facade or other structure would then be more than something to dispose of at the end of its life: it would be a potential future raw material.
New business models could emerge from this. Manufacturers might develop an interest in recovering materials after their first use phase and feeding them back into their own production. Buildings would no longer be seen as the final destination for construction materials, but as a temporary place of use.
Recycling need not necessarily entail a substantial price premium in future. According to Holcim's calculations, recycled concrete can cost the same as conventional concrete depending on the circumstances and raw-material availability. In some cases it is a few per cent more expensive - well below five per cent, in the experts' assessment - and in certain situations it can even be cheaper. Factors include transport distances and the processing business model: recycling companies can earn revenue both from accepting the original material and from selling the processed construction material.
The public sector can create demand
The public sector could play a key role in expanding the market. In 2024 alone, public construction contracts worth €47.7 billion were reported, according to the Federal Ministry for Economic Affairs' procurement statistics. A study published in 2025 by the Wuppertal Institute and Butterfly Effect Consulting, commissioned by Holcim Germany, identifies this as a key driver of the transition in construction materials. Its recommendations include embedding sustainability criteria more firmly in public tenders and creating economic conditions that facilitate investment in circular production processes and construction materials.
Planning certainty is particularly important for processing companies: the study notes that companies postpone investment in modern recycling plants when it is unclear whether there will be a lasting market for the secondary construction materials produced.
Public investment in refurbishing roads, bridges, buildings and other infrastructure could therefore have an impact beyond individual projects. Reliable demand for recycled construction materials creates sales opportunities and can stimulate further investment in processing and production capacity. Federal, state and local authorities are therefore called on to use their role as clients and contracting bodies strategically.
The success of the circular economy is thus no longer determined by technical feasibility alone. New concrete can already be made from old concrete. For this to happen at greater scale, however, reverse logistics, quality control, standards, digital information, economic incentives and reliable demand must work together.
Demolition material must reliably return, manufacturers must be able to turn it into quality-assured products, and those products need buyers. Recycling can only grow to the necessary scale when this cycle also works economically.
Selecting a construction material could therefore involve an additional question in future: what could this material become when the building no longer needs it?